

Karl's Mortgage Calculator Pro
Dr Karl Jeacle
- 4.6
- 88.00 Reviews
- 10.00K
- Downloads
- $2.49
- Price
Screenshots
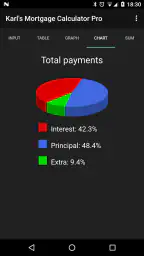
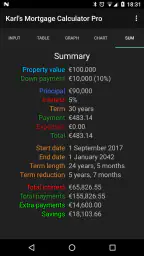
Karl's Mortgage Calculator Pro Pros and Cons
Pros
- Supports extra payments and shows their effect on payoff time.
- Includes property tax, insurance, and other recurring housing costs.
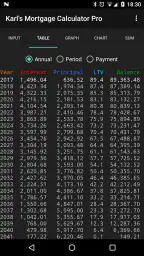
- Useful amortization breakdown helps track principal and interest over time.
- Clean interface makes common mortgage calculations quick to enter.
- Pro version avoids distracting ads during financial planning.
Cons
- May not include current lender rates or live mortgage offers.
- Advanced users may miss refinancing and loan-comparison scenarios.
- Results depend on accurate inputs and do not replace lender estimates.
- Currency and regional tax options may be limited for some users.
- Some users may find the interface dated compared with newer finance apps.
 Analysis by All-app
I tend to distrust mortgage calculators that reduce a major borrowing decision to one large monthly-payment figure. That number matters, but it is only the beginning: the balance changes over time, interest can dominate the early years, and small changes in term or rate can alter the total cost dramatically. Karl's Mortgage Calculator Pro takes a more analytical approach. It is a finance app from Dr Karl Jeacle built around mortgage calculations, with graphs and charts intended to make the repayment journey easier to inspect rather than leaving everything in a plain result box.
After spending time with it, my impression is that this is a focused tool for people who want to understand a loan, not a general personal-finance dashboard. It feels most useful when I am comparing scenarios, checking whether a proposed payment is realistic, or trying to explain the difference between shortening a term and making occasional extra payments. The app is available for $2.49, carries an Everyone age rating, and has a 4.6 average from around 222 ratings. Those details suggest a small but clearly interested audience rather than a mass-market budgeting product.
How the calculator feels in current use
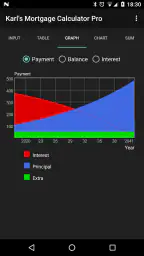
The strongest part of Karl's Mortgage Calculator Pro is its emphasis on visual interpretation. A conventional calculator can tell me how much I would pay each month, but a chart can show why that payment behaves the way it does. Seeing the relationship between principal and interest over the life of a mortgage gives the result more meaning. I can move from “what is the payment?” to “how quickly does the balance fall?” and “how much of the early repayment is interest?”
That distinction is important for first-time buyers. Someone who has never examined an amortization schedule may assume that every payment reduces the loan by roughly the same amount. A graph makes it easier to see that the split changes over time. I find that particularly helpful when comparing a longer mortgage with a shorter one: the shorter option may require more room in the monthly budget, but the visual cost of extending the term can be much clearer than it is in a single total.
The app’s identity is deliberately narrow. It is not trying to combine mortgage planning with bank accounts, spending categories, investment tracking, or credit monitoring. For me, that is a benefit when I am concentrating on one borrowing decision. It also means that anyone looking for a complete household finance system will need another app or a spreadsheet alongside it.
A realistic use case would be a couple preparing for a meeting with a lender. Before discussing a purchase price, I would enter several possible loan amounts and terms, then compare the resulting payment patterns. I would save the figures or note them separately, because the real value is not choosing one magical answer inside the app; it is arriving at the conversation with better questions. Can we comfortably handle the payment if other costs rise? Is the lower monthly amount worth the extra interest? Would a modestly larger payment materially change the end date?
The graphs are most valuable when used for comparison, not decoration. I would not open the app merely to calculate a number I can obtain from a search engine. I would use it when I need to study how several assumptions interact. That is where the product earns its place on my phone.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
What the visual approach changes
Charts also help prevent a common planning mistake: focusing only on affordability today. A payment can fit a current budget while still producing an unnecessarily expensive loan over time. By looking at the repayment path, I can judge the trade-off between a comfortable monthly obligation and the total cost of borrowing. This is not a substitute for advice from a lender or financial professional, but it is a useful way to make the conversation less abstract.
Another practical benefit is that the app encourages me to test sensitivity. Instead of assuming that one interest rate is permanent, I can examine how the outcome changes when the rate or term changes. Even when a mortgage product has a fixed period, that exercise helps expose how dependent the plan is on a particular assumption. I would treat every result as a model, not a promise, especially where a lender uses different compounding conventions, fees, insurance, or repayment rules.
This is also where the calculator may be more useful to an existing homeowner than to a prospective buyer. A homeowner can use it to think through refinancing, a change in term, or the effect of paying more than the required amount. The key is to compare like with like. If I alter the rate, term, and payment at the same time, I may get an impressive-looking result without knowing which change caused it. I prefer to change one assumption first, record the result, and then build a second scenario.
What has changed and how to read the app’s maturity
Karl's Mortgage Calculator Pro was released on May 13, 2012, so it is not a new arrival built around the latest mobile-finance trends. Its long presence is part of the product’s character: the app is centered on a specific calculation problem rather than constantly expanding into unrelated financial services. The current store identity still presents it as an advanced mortgage calculator with graphs and charts, which matches the experience I would want from a specialist tool.
That history should shape expectations. I would not choose it because I want a glossy financial platform with a social layer, automatic account connections, or a stream of personalized offers. I would choose it because a dedicated calculator can remain easier to understand than a large finance app filled with features I do not need. The developer, Dr Karl Jeacle, has kept the product associated with its original purpose, and that focus is more meaningful to me than a long list of fashionable extras.
The app has reached over ten thousand installs, while its review volume remains relatively modest. I read that combination as evidence of a niche utility with a committed audience, not as a reason to assume it suits every borrower. A specialist calculator can be excellent for careful scenario testing and still be the wrong tool for someone who wants automated data import or a guided mortgage application.
For existing users, the main advantage of this focused design is continuity of purpose. If I already use it to inspect repayment scenarios, I do not have to relearn a budgeting ecosystem every time I want to revisit a loan question. I can return to the same kind of analysis when my circumstances change. That simplicity is valuable during a refinancing discussion, when the important task is comparing assumptions rather than exploring a crowded interface.
There is a trade-off, though. A calculator that has remained narrowly focused may require more discipline from me. I need to know which figures to enter, understand what the result represents, and keep notes if I want to compare scenarios later. A modern financial app may offer more guidance or connect directly to an account, while this tool puts more responsibility on the user. I see that as acceptable for an informed borrower, but it could feel demanding for someone who wants the app to explain every term.
A useful workflow for buyers and homeowners
My preferred workflow begins with a baseline scenario. I enter the proposed borrowing amount, rate, and repayment term, then examine both the payment and the visual schedule. I write down the result before changing anything. Next, I test a shorter term without changing the other assumptions. After that, I try a slightly different rate. This order makes it easier to see whether affordability is being improved by paying faster or simply by assuming cheaper borrowing.
For an existing mortgage, I would create a separate baseline using the current balance rather than the original loan amount. That small distinction matters: entering the original amount can make a current decision look far more expensive than it really is. I would then compare an extra-payment scenario with a term-change scenario. The two may produce similar outcomes in some cases, but they do not necessarily offer the same flexibility, and the lender’s rules must be checked outside the app.
A less obvious tip is to use the charts as a communication tool. If one person in a household is comfortable with financial formulas and the other is not, a visual repayment path can make the discussion less confrontational. Instead of arguing over whether a longer term “feels” expensive, we can look at how the balance and interest evolve. I still would not treat the chart as a verdict, but it gives both people a shared starting point.
Another worthwhile habit is to model a deliberately uncomfortable case. I might test a higher rate or a shorter income period to see whether the plan still leaves breathing room. The purpose is not to predict the worst possible future; it is to discover whether the budget depends on everything going perfectly. A calculator becomes much more useful when it challenges an optimistic assumption instead of merely confirming it.
Where it compares well with ordinary alternatives
The usual alternative is a web-based mortgage calculator. Those tools are convenient for a quick estimate, especially when I am browsing properties and do not want to install anything. They can be better for a first-pass answer or for calculators tied to a particular lender’s products. However, many web tools are designed to produce a headline payment quickly. A dedicated app with charts is more appealing when I want to revisit a scenario away from a browser and inspect the repayment pattern in greater depth.
A spreadsheet is the other serious alternative. Spreadsheets offer more control, especially if I need to add taxes, insurance, fees, irregular payments, or several income scenarios. They are also better for building a complete household model. The cost is setup time and the risk of formula mistakes. Karl's Mortgage Calculator Pro is more convenient for the core mortgage question because the calculation environment is already prepared, while a spreadsheet becomes stronger once the problem extends beyond the loan itself.
General budgeting apps are useful for answering a different question: whether the payment fits into the household’s broader spending pattern. They may show cash flow, subscriptions, savings, and bills, but they often do not provide the same focused view of amortization. I would use a budgeting app to understand affordability and this calculator to understand the loan. Neither replaces the other.
For a borrower who wants speed above all else, the app may feel like more than necessary. If I only need a rough monthly estimate while browsing listings, a web calculator is probably quicker. If I need lender-specific fees, current product terms, or automatic account data, another service may be a better fit. The specialist nature that makes this app useful for analysis also limits its appeal as an all-purpose financial companion.
Remaining gaps and practical cautions
The first limitation is that a mortgage model is only as reliable as its assumptions. Real loans can involve fees, taxes, insurance, changing rates, payment-frequency differences, penalties, and lender-specific treatment of extra payments. I would never use the app’s output as a final approval figure or assume that a chart captures every cost in an offer. It is a planning instrument, not a contract interpreter.
The second limitation is workflow. I would like to be careful about how I preserve and label several scenarios, because mortgage comparisons become confusing quickly. A buyer may have one result for a current home, another for a larger deposit, and a third for a different term. Without clear notes outside the calculator, it is easy to remember the attractive payment while forgetting the assumptions behind it. That is not a flaw in the arithmetic, but it is a real friction point in practical use.
There is also a learning curve hidden behind the word “advanced.” Someone familiar with amortization will appreciate the depth more quickly. A beginner may see charts without immediately knowing which one deserves attention or why the interest portion changes. I recommend approaching the app with one concrete question rather than opening it with no plan. For example: “How much does shortening the term change the total interest?” A focused question makes the screens easier to interpret.
Privacy-conscious users may also prefer a calculator that does not require them to connect financial accounts, because manual scenario planning keeps the exercise separate from everyday banking. On the other hand, manual entry means I must supply accurate figures myself. I would check the balance, rate, and remaining term directly against the lender’s documents before trusting a comparison.
The age rating of Everyone makes the app broadly approachable, but that should not be confused with financial simplicity. A teenager can open a mortgage calculator, yet a responsible adult still needs to understand the assumptions and consequences. The app presents calculations; it does not turn a complicated borrowing decision into a risk-free one.
Who should use it and who should skip it
I would recommend Karl's Mortgage Calculator Pro to a buyer who enjoys comparing options, an existing homeowner considering a change, or anyone who wants a clearer picture of principal and interest over time. It is particularly suitable for people who are comfortable entering figures manually and who value charts more than automated account features. The one-time price of $2.49 is easy to justify if I expect to use the tool for several serious mortgage decisions rather than a single curiosity.
I would steer a casual user toward a simpler alternative if all they need is a rough payment estimate. I would also suggest a spreadsheet or broader finance app to someone building a full household affordability plan that includes utilities, maintenance, taxes, insurance, savings, and irregular income. The calculator can inform that plan, but it should not be mistaken for the plan itself.
People dealing with unusual repayment structures should be especially cautious. If the loan includes features that do not fit a straightforward model, I would verify the result with the lender and, where appropriate, a qualified adviser. The app is strongest when the question is a clear comparison between standard mortgage assumptions; it becomes less suitable when the contract contains conditions that require specialist interpretation.
What I would watch before relying on it long term
When I revisit a finance app that has been available since 2012, I look for whether its core purpose still matches my needs and whether its presentation remains understandable. Here, the central promise remains clear: mortgage calculations supported by graphs and charts. I would watch for improvements that make scenario comparison easier without turning the app into a distracting financial portal. Better organization, clearer explanations of assumptions, and smoother handling of repeated comparisons would matter more to me than unrelated additions.
I would also pay attention to how well the tool fits changing mortgage habits. Borrowers increasingly compare fixed periods, refinancing choices, and extra-payment strategies, but those decisions still depend on the exact loan contract. The most useful evolution would be anything that helps users distinguish a simple mathematical projection from a lender-specific outcome. Until then, I would keep treating every chart as an informed estimate and verify important conclusions elsewhere.
My final view is positive, with a clear qualification. Karl's Mortgage Calculator Pro is not a replacement for a lender, adviser, spreadsheet, or household budget. It is a focused companion for understanding the shape and cost of a mortgage. I like that it encourages me to look beyond the monthly payment and examine how the balance changes. If you want a quick number, there are easier choices. If you want to think carefully about terms, rates, repayment speed, and the cost of borrowing, Karl's Mortgage Calculator Pro offers a practical, inexpensive way to do that. For me, its best feature is not any single figure; it is the habit of asking better questions before committing to a loan.
Frequently Asked Questions
What is Karl's Mortgage Calculator Pro used for?
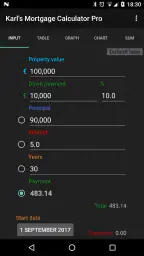
Karl's Mortgage Calculator Pro is designed to help users estimate mortgage payments and understand the cost of borrowing. You can typically enter details such as the property price, down payment, interest rate, loan term, and payment frequency. The app is useful for comparing different scenarios before speaking with a lender, although its results should be treated as estimates rather than an official loan offer.
Can the app calculate more than the basic monthly mortgage payment?
Yes, one of the main advantages of a dedicated mortgage calculator is that it can show more than a single payment figure. Depending on the options available in the installed version, Karl's Mortgage Calculator Pro may help estimate principal and interest, amortization over time, total interest, and the effect of changing the loan term or interest rate. Users should verify whether taxes, insurance, fees, and other local costs are included.
Is Karl's Mortgage Calculator Pro suitable for different loan types and payment schedules?
The app can be useful for testing a variety of mortgage situations, including different loan amounts, interest rates, terms, and payment frequencies. This makes it practical for comparing potential offers or checking how extra payments could affect repayment. However, mortgage rules and calculation methods vary by country and lender, so users should confirm that the app's settings match their local loan system.
Does Karl's Mortgage Calculator Pro provide accurate financial advice?
The calculator can produce helpful estimates when the information entered is correct, but it should not be considered personalized financial advice. Actual mortgage payments may differ because lenders can apply different compounding methods, fees, insurance requirements, taxes, discounts, and eligibility conditions. Before making a purchase or refinancing decision, compare the results with official lender documents and consult a qualified mortgage professional.
Is Karl's Mortgage Calculator Pro easy to use, and what information should I prepare?
The app is intended to make mortgage calculations straightforward, even for users who are not familiar with financial formulas. To get useful results, prepare the home price or loan amount, expected down payment, interest rate, repayment period, and preferred payment frequency. For a more realistic estimate, also consider property taxes, homeowners insurance, mortgage insurance, closing costs, and any additional payments.


